Will a New Roof Replacement Raise Insurance Premiums or Lower Them?
Homeowners ask us all the time whether a roof replacement will raise insurance premiums, and the honest answer is that it depends on what goes on the roof. Impact-resistant materials can drop your premium by up to 35% because they cut the insurer's risk. Go the other direction and upgrade to slate or tile, and your home's replacement value goes up, so your rate can climb to cover that new worth. Check whether the material you pick qualifies for weather-resistance discounts before you sign a contract.
How Insurance Companies Look at Your Roof
How Do Insurance Companies Assess Risk?
Insurers use actuarial data to predict how likely your home is to be damaged. They compare your property to thousands of similar homes around Tulsa. An older roof, or one built from materials that fail in Oklahoma storms, is a bigger liability. They calculate the odds of a catastrophic failure. They want to know whether your roof can take wind or hail without a total payout. Based on the structural integrity and resistance ratings of your roofing system, they assign a risk score. A higher score means you pay more every month.
What Roof Factors Influence Your Premium?
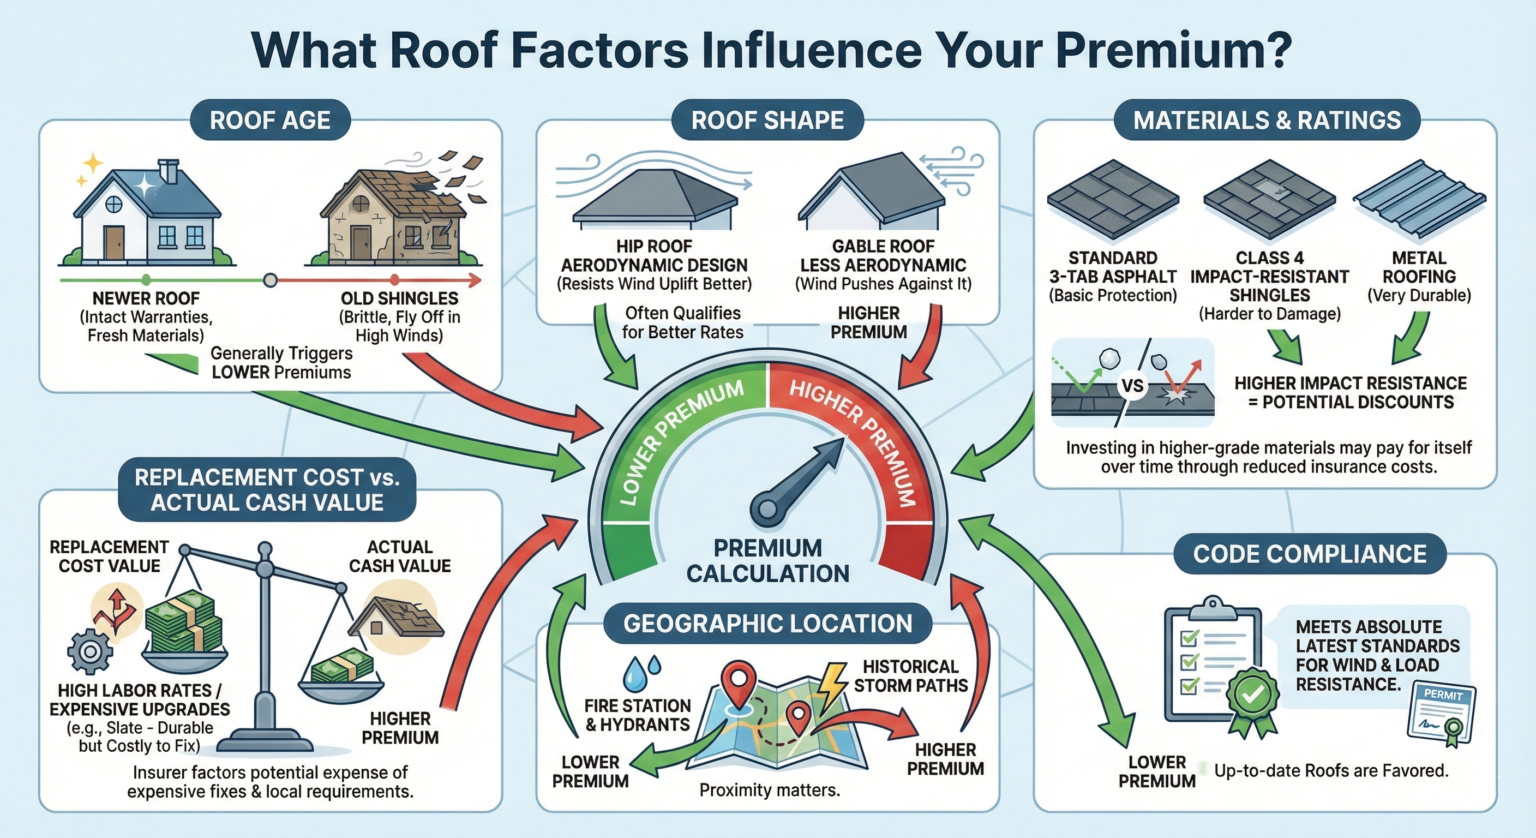
Age is the first thing an underwriter checks. Old shingles are brittle and can fly off in high winds. Shape matters too. A hip roof, which slopes on all four sides, is more aerodynamic than a gable roof and often earns better rates. Wind cannot push against it as easily.
Materials are the other big variable. Standard 3-tab asphalt shingles give you basic protection. Class 4 impact-resistant shingles or metal roofing change the calculation. They are harder to damage, so you are less likely to file a claim over minor hail.
- Roof Age: Newer roofs generally trigger lower premiums thanks to intact warranties and fresh materials.
- Roof Shape: Aerodynamic designs like hip roofs resist wind uplift better than gable ends.
- Material Ratings: Higher impact resistance ratings correlate directly to potential discounts.
Higher-grade materials usually pay for themselves over time through reduced insurance costs.
You also have to weigh replacement cost value against actual cash value on the new system. In an area with high labor rates, or where local building codes require expensive upgrades, the insurer has to build that potential expense into your premium. Slate is durable, but it is also expensive to fix when a tree falls on it. That complicates how the premium gets calculated.
- Geographic Location: Proximity to fire stations, hydrants, and historical storm paths.
- Replacement Cost: The current market price to replace the specific materials you chose.
- Code Compliance: Whether your roof meets the latest standards for wind and load resistance.
Your agent will not know about any of these improvements unless you hand over the documentation.
Can a New Roof Actually Lower Your Insurance Costs?
Most home improvements only drain the savings account. A new roof is one of the few that can put money back in your pocket over time. Insurers bet against disasters, so they like anything that lowers the odds of a payout. A modern, sturdy system is less of a liability than worn-out shingles.
From their side of the table, old roofs are a major source of water damage claims. A brand-new installation is solid protection against the elements. Because you lower the risk of leaks and structural failure, many carriers pass some of those savings back to you.
The Discounts You Might Get
Your annual rate can drop a lot. Some carriers offer reductions from 5% up to 35%, depending on the policy. Those discounts are tied to specific upgrades that reduce weather risk, like impact-resistant shingles that stand up to hail.
Usually you have to ask. You will need to prove the new roof meets the standard, often with an installation certificate or an impact-resistance rating form from your contractor. Send the paperwork in as soon as the project wraps up.
What Materials Could Save You Money?
For the biggest discount, standard asphalt shingles may not cut it. Look at Class 4 impact-resistant options. They are built for severe weather, and insurers reward that durability. You can find Oklahoma impact-resistant shingles insurance discounts up to 25% from various carriers. Metal roofing is another strong option, often earning substantial premium breaks because it resists fire and holds up to wind.
These materials cost more upfront, but the long-term math can work in your favor once you count years of lower insurance bills. Before you sign a contract, call your agent and run the numbers on different material types. Spending a little extra on hail-resistant materials can pay for itself faster than you expect.
The top layer is not the whole story. Secondary water barriers and wind-mitigation attachments can trigger discounts even with traditional shingles. Upgrading your roof deck attachment or using better underlayment strengthens the whole system against storms, and that is what adjusters want to see.
When Could Your Premium Go Up After a Roof Replacement?
It feels backwards to spend thousands on a new roof and then watch the insurance bill climb. It happens more than you would think. The usual reason is an increase in your home's replacement cost value. If the old roof was worth $10,000 and the new system is worth $25,000, your carrier has a more expensive asset to cover. So when you ask how much does home insurance go up after a new roof, the answer rides on that new value. Nobody is penalizing you for the upgrade. They are recalculating the financial risk.
When the condition of your home improves, the dwelling coverage limit often has to rise to match the new appraisal value. That adjustment keeps you from being underinsured, and it also raises your monthly premium. You have a safer home, and you are paying to insure a higher-value property.
Is It All About Upgrades?
Switching from standard asphalt shingles to slate, clay tile, or heavy-gauge metal changes the math for your insurer. Those materials hold up well to Tulsa weather, but they are also far more expensive to repair or replace. Swap basic composite shingles for a luxury slate roof and your premium may rise to match the higher tier of coverage required.
It is a trade-off. A premium roof lasts longer, and you may pay more each year to insure it. If a hailstorm cracks expensive tiles, the payout is huge compared to a standard shingle roof, and your premium reflects that. Decide whether the longevity and curb appeal are worth the potential increase.
What If You Uncover Problems While Replacing?
Pulling off old shingles can expose rot or bad decking. If the damage is severe, you may have to file an additional claim to cover the repairs. That extra claim activity can read as higher risk to your insurer. Carriers get nervous when they see deep structural issues, because it can point to years of deferred maintenance.
Finding those issues can also trigger a mandatory re-inspection. Your insurer may want proof of repairs before renewing the policy. If your contractor finds significant water damage in the trusses, the company might require detailed documentation showing the structure was fully restored. Ignoring those problems risks more than a premium hike. It can make coverage hard to get at all.
Timing Your Roof Replacement for Insurance Wins
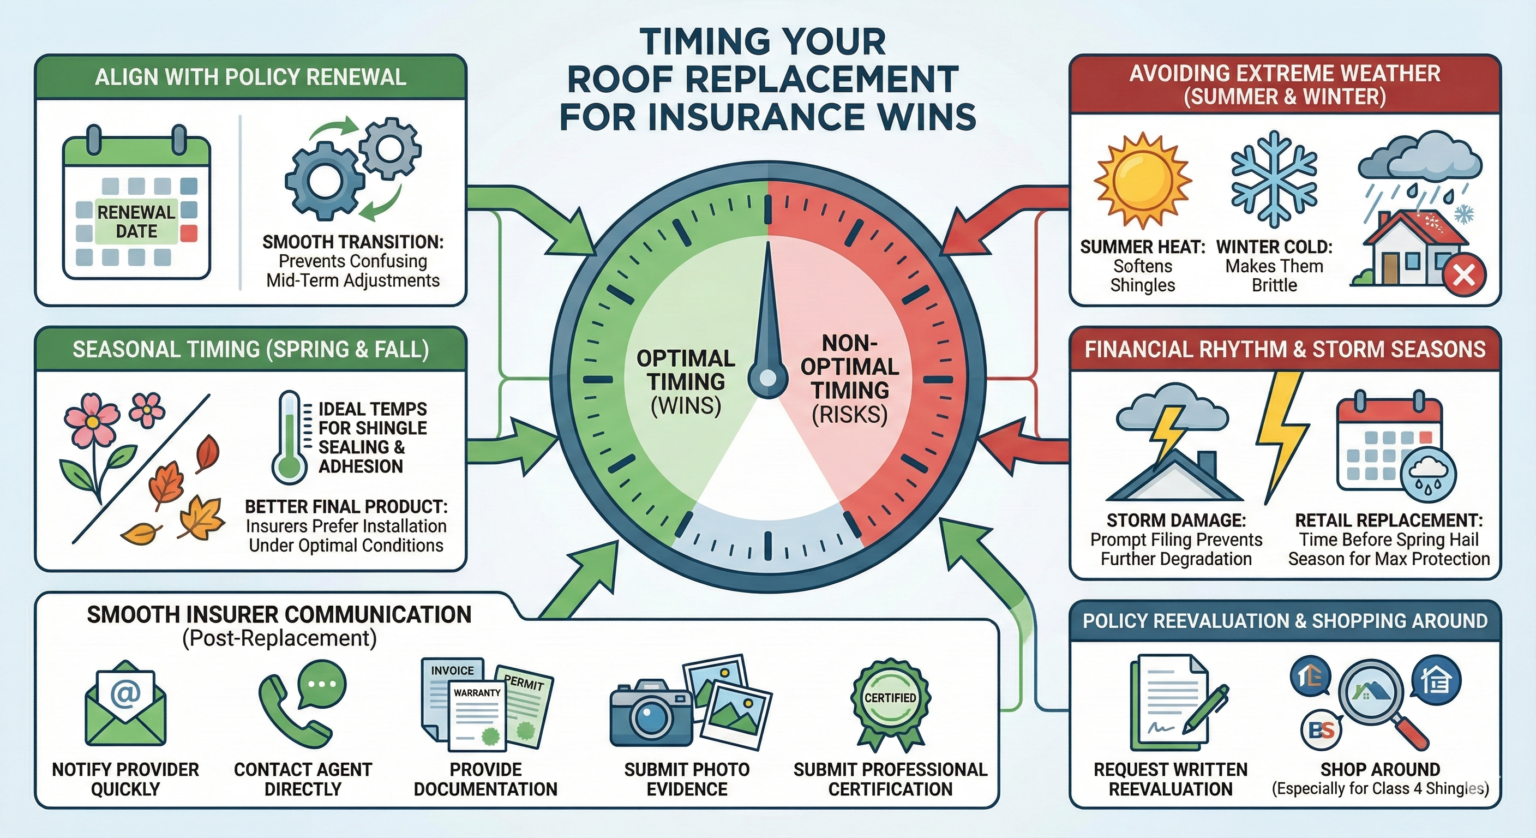
When you replace the roof affects the benefits you get. Lining the project up with your policy renewal date gives your insurer time to adjust coverage before the next billing cycle. That avoids confusing mid-term adjustments.
Oklahoma weather should shape your timing too. Spring or fall gives you ideal temperatures for shingle sealing and adhesion. You skip the summer heat that softens shingles and the winter cold that makes them brittle. Adjusters like to see an installation done under good conditions.
Is There a Perfect Time to Replace Your Roof?
You can replace a roof in anything but rain or snow, but mild spring or autumn weather usually produces a better final product. Insurers favor roofs installed under optimal conditions because it means fewer workmanship claims down the road. Staying out of peak storm season also means your Tulsa roofing contractor is not rushing your job to get to the next emergency repair.
There is a financial rhythm to it as well. If storm damage is driving the work, filing the claim and scheduling the job quickly prevents further degradation your insurer might later refuse to cover. If you are paying out of pocket, getting it done before spring hail season means the new impact-resistant materials are protecting you when you need them most.
How to Keep Things Smooth with Your Insurer
Once the roof is finished, tell your insurance provider right away so you can lock in any premium reduction. Call your agent directly. Give them the materials used, the installation date, and the name of your Tulsa roofing contractor. Have your documentation ready: the contractor's final invoice, material warranties, and building permits.
Thorough evidence helps. Many carriers now want photos of the completed roof. Include clear images showing the full roof from several angles. A professional roof certification from your contractor often speeds up the premium adjustment and helps you capture every discount you qualify for.
If your agent is slow to respond or tells you nothing will change, ask for a written reevaluation of your policy. Carriers around Tulsa treat this differently. Some place more value on materials that handle Oklahoma weather. If you installed Class 4 shingles and your insurer offers nothing for it, it may be time to shop around.
Talking to Your Insurance Company
You have to advocate for yourself here. Carriers do not watch your property for improvements. Until you tell them, they keep billing you based on the old, riskier roof. You are not asking for a favor. You are showing evidence that your home is safer to insure.
The homeowners who do best treat the conversation like a business negotiation. You installed materials built for Tulsa weather. Make sure your agent understands the roof is not just new, it is built to handle the exact threats that cause claims.
What Info Do You Need to Share?
Calling to say you have a new roof will not get you savings on its own. You need proof. The key document is the Impact Resistance Certificate from the shingle manufacturer. Your roofing contractor should hand it over at completion. It verifies the materials meet the UL 2218 Class 4 standard for hail resistance, and it is often required for the discount.
Along with the certificate, send the final paid invoice and the permit completion sign-off. Add a few clear, high-resolution photos of the finished work, including close-ups that show installation quality. That digital paper trail gives the underwriter everything needed to recalculate your rate.
Should You Shop Around for Better Rates?
Loyalty does not always pay in insurance. Carriers have different appetites for Oklahoma risk. Yours might offer 5% for an impact-resistant roof. A competitor might offer 25% or 30% for the same protection.
If the quote after your investment is underwhelming, look elsewhere. Quotes are free. Use the new roof as leverage with other brokers. Tell them you just installed a fortified roof system and you want to know who gives the best credit for it. Switching could save you hundreds a year.
Do not judge on price alone. Sometimes a cheaper premium means the new company writes "Actual Cash Value" coverage on your roof instead of "Replacement Cost." Make sure the lower rate still includes full replacement cost coverage, or you will be holding a big bill after the next storm.
Common Myths About Roof Replacements and Insurance
Online forums are full of conflicting stories. You might land on a thread asking, Insurance premium increased after roof replacement? and start worrying. That advice usually lacks nuance, because every policy and every location is different.
Some homeowners think telling their insurer about a new roof is risky. Hiding a major improvement is riskier. Your carrier needs accurate data to cover you properly. Outdated information costs you money, either in missed discounts or denied claims.
Do New Roofs Always Mean Higher Rates?
Replacement cost coverage is usually behind a rate hike, not the new roof itself. Swap standard asphalt shingles for high-end slate and you have raised the value of the asset the insurer has to protect. They charge more because rebuilding that slate roof costs more than rebuilding the old asphalt one.
The good side gets ignored. A new roof lowers the risk of water damage claims. Your dwelling coverage amount may rise while your rate per $1,000 of coverage drops, because the home is safer. It is a balancing act, and assuming the rate will skyrocket keeps people from making upgrades they need.
What Most People Get Wrong
Actual Cash Value policies trip up a lot of homeowners. You may think you have full replacement coverage, but on an ACV policy a 15-year-old roof only pays what that old roof is worth today. Plenty of people assume a new roof automatically switches them back to replacement cost coverage without a call to the agent. You have to request that change.
Another myth is that discounts are automatic because the roof is new. They are not. Without the specific impact-resistance certification, like a UL 2218 Class 4 form, the system just sees "new roof." You leave money on the table by skipping the engineering paperwork that proves your shingles can take hail.
Grandfathered rates matter too. You may hold a loyalty rate that no longer exists for new policies. A big change like a roof replacement can trigger a policy rewrite at current market rates. That is not the roof's fault, but it is what prompts the update. Ask your agent whether updating your roof details will trigger a full rewrite, so your base rate does not surprise you.
A roof replacement is more than a construction project. It is a financial decision that changes your monthly costs. You may worry about a rate hike, but insurers would rather cover a secure home that can take a Tulsa storm. If your premium goes up, it is usually because your home is worth more, and that is a good outcome.
The only real mistake is staying silent.
Call your agent when the work is done. Ask about Class 4 impact ratings and wind mitigation credits. Make them explain how the new roof changes your policy's math. You spent money protecting your biggest asset, so make sure your carrier knows it. If you want help sorting out whether a roof replacement will raise insurance premiums on your policy, our team at Trifecta Roofing can walk you through it. Talk to one of our experts to get a quote for roof replacement without raising insurance premiums.
Ready to protect your home and possibly lower your insurance costs? Get your free quote from Trifecta Roofing today.
FAQ
Will getting a new roof actually drop my insurance bill?
Insurers see old roofs as a high liability. A new roof is lower risk because it is less likely to leak in a storm. You will probably see some savings. How much depends on the materials. Basic shingles earn a small discount. Impact-resistant materials earn much more. Ask your agent about specific discounts before you pick materials.
Is there any world where my premium goes up after a replacement?
Replacing a standard shingle roof with the same material usually lowers rates. Upgrading to slate or tile is a different story. Those materials cost more to repair. Your premium may rise to cover the higher replacement cost. You get a better roof and may pay a bit more to insure its value.
Are impact-resistant shingles really worth it for insurance?
Yes. Standard shingles can be damaged by hail. Class 4 impact-resistant shingles are built for severe weather. Insurers value that durability because it means fewer claims. In Tulsa, discounts for these materials can be substantial, often 20% to 35%. The upfront cost is higher, and the long-term savings plus the added protection are worth it.
When should I tell my insurance company about the new roof?
Call as soon as the project is finished. Waiting for your renewal means months of overpaying. Get the certificate of completion from your contractor and send it to your agent right away. Ask when the new rate takes effect. The change is often prorated, and you may get a refund.
What if I get a new roof and my insurer does not drop my rate?
If a major upgrade earns you nothing, shop around. Carriers do not evaluate risk the same way. One may offer no discount while another does. Use your new roof certification to get quotes from other companies. You may find a better rate for the same coverage.