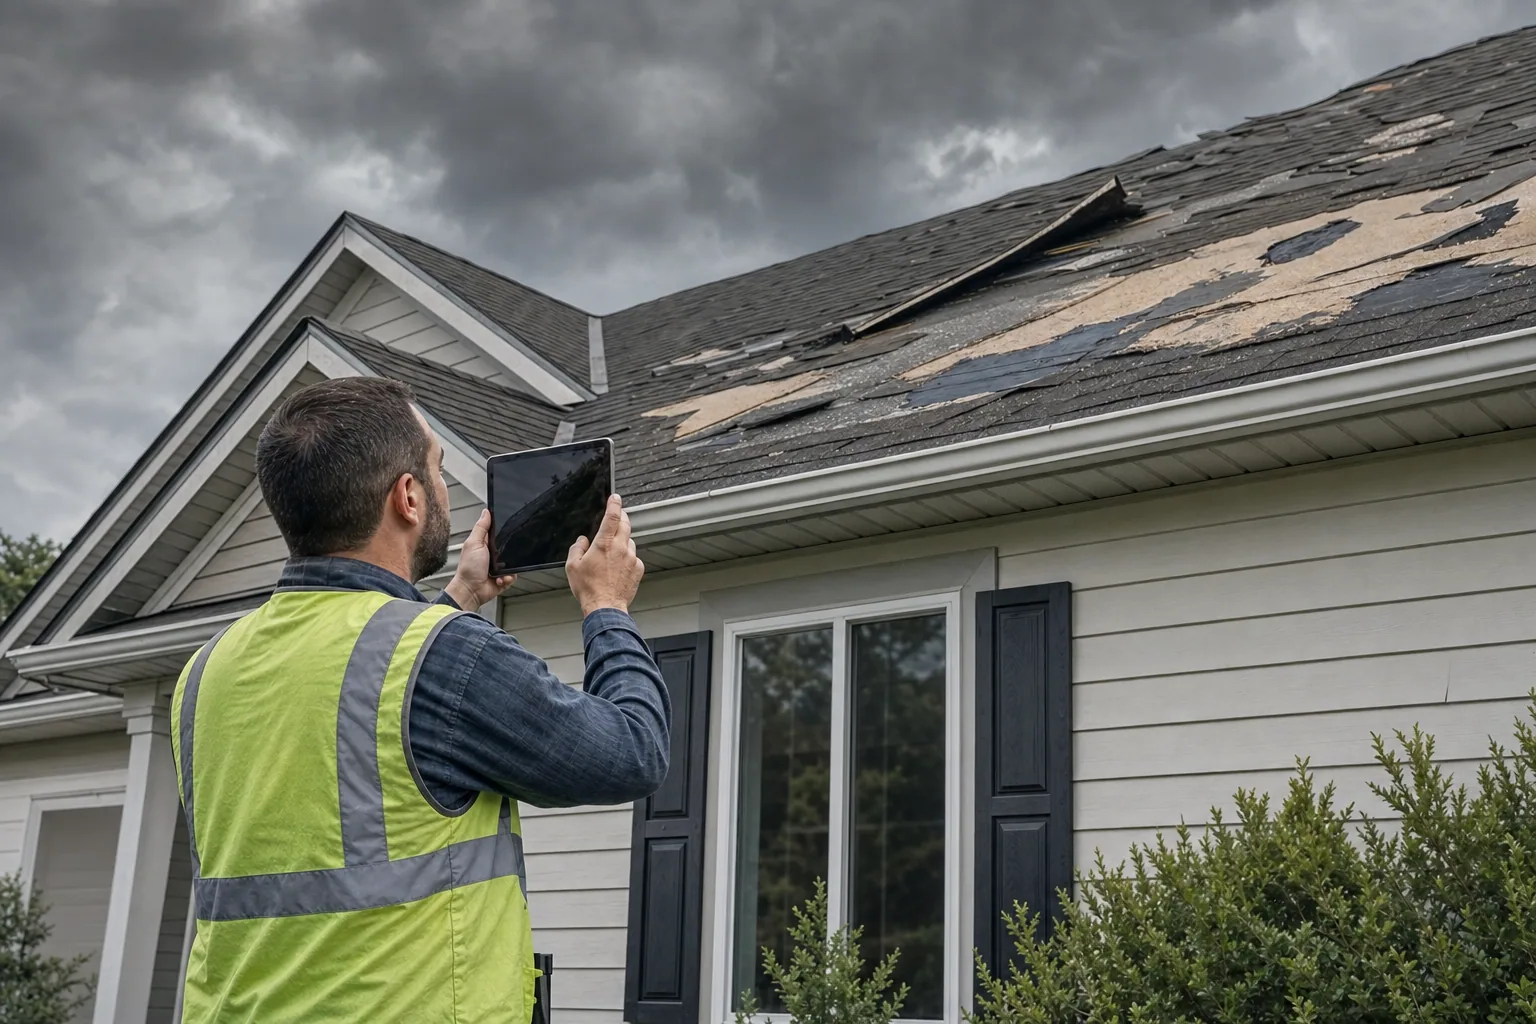
TL;DR: To file a wind damage roof insurance claim, photograph the damage before anyone touches the roof, report it to your insurer within the window your policy requires, and have a roofer present when the adjuster inspects. Documentation filed early is what separates a paid claim from a denied one.
When a severe windstorm hits Tulsa, your roof often takes the hit first. Wind damage can range from a few missing shingles to structural failure, and most homeowners don't know where to start when filing an insurance claim. Understanding the process and preparing properly can make the difference between a denied claim and one that covers most or all of your repairs.
This guide walks you through filing an insurance claim for roof wind damage, what insurers look for, and how to protect your claim from the moment the storm passes.
How Do I File a Wind Damage Roof Insurance Claim?
Here is the whole process in order, before we get into the detail of each step.
- Document the damage first. Photos and video from the ground, wide shots and close-ups, before anyone gets on the roof.
- Report the claim to your insurer. Have your policy number ready and give them the date of the storm.
- Make safe temporary repairs only. Tarp or patch to stop water getting in, keep the receipts, and leave the real repairs alone until the adjuster has been out.
- Be there for the adjuster's inspection. Walk the damage with them, and have your roofer there too if you can.
- Compare the estimate to a roofer's scope. If the numbers don't line up, submit a detailed contractor estimate and ask for the difference to be explained.
What the timeline usually looks like
| Stage | When it happens |
|---|---|
| Spot and document damage | Same day, if it is safe to do so |
| Report the claim | Most policies require notice within a specific timeframe, typically 30 to 60 days |
| Adjuster inspection | Scheduled by your insurer after you file |
| Settlement issued | One check for the full estimate, or an initial payment plus a second check after repairs |
| Repairs completed | Many policies require the work to be done within a certain timeframe, typically 6 months to 2 years |
If your first question is whether wind is covered by your policy at all, start with our guide to what homeowners insurance covers on a roof. If you already know shingles are gone and you want someone to look at the roof, our roof repair and replacement crew can inspect it and document what we find for your claim file.
What Counts as Wind Damage for Insurance
Not every roof problem is covered under your homeowners insurance policy. Wind damage claims specifically cover harm caused by high-velocity winds, not wear and tear or poor maintenance.
Insurers typically recognize wind damage when:
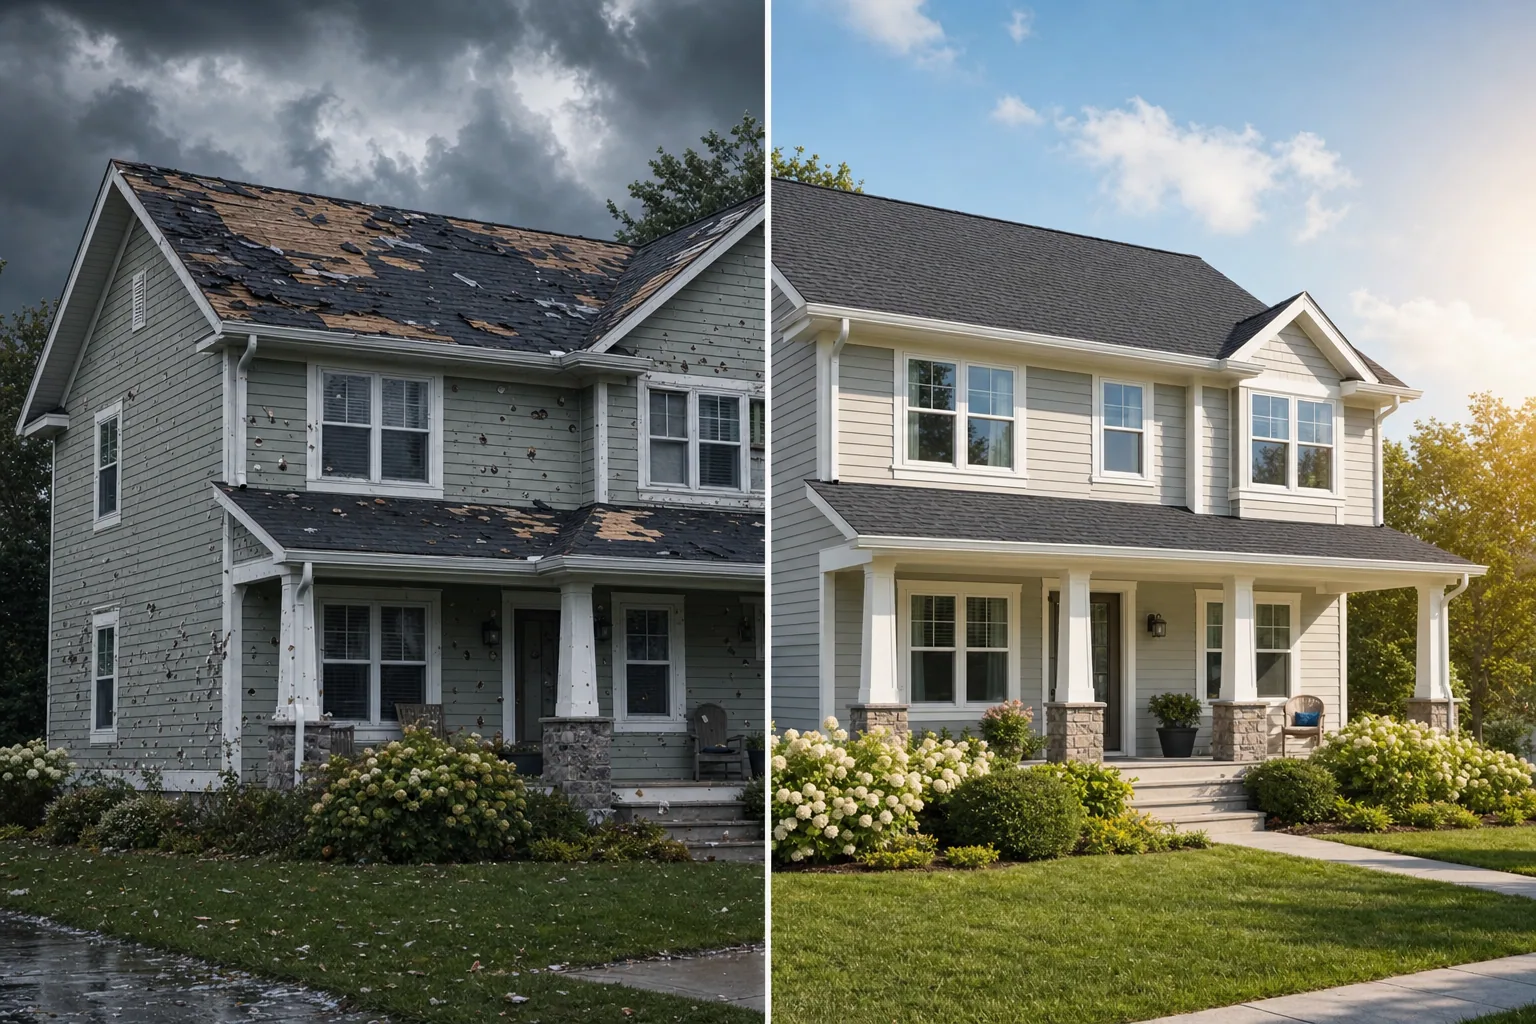
- Shingles are lifted, curled, or missing entirely
- Flashing is bent or separated from the roof
- Gutters or downspouts are bent or detached
- Fascia boards are cracked or pulled away
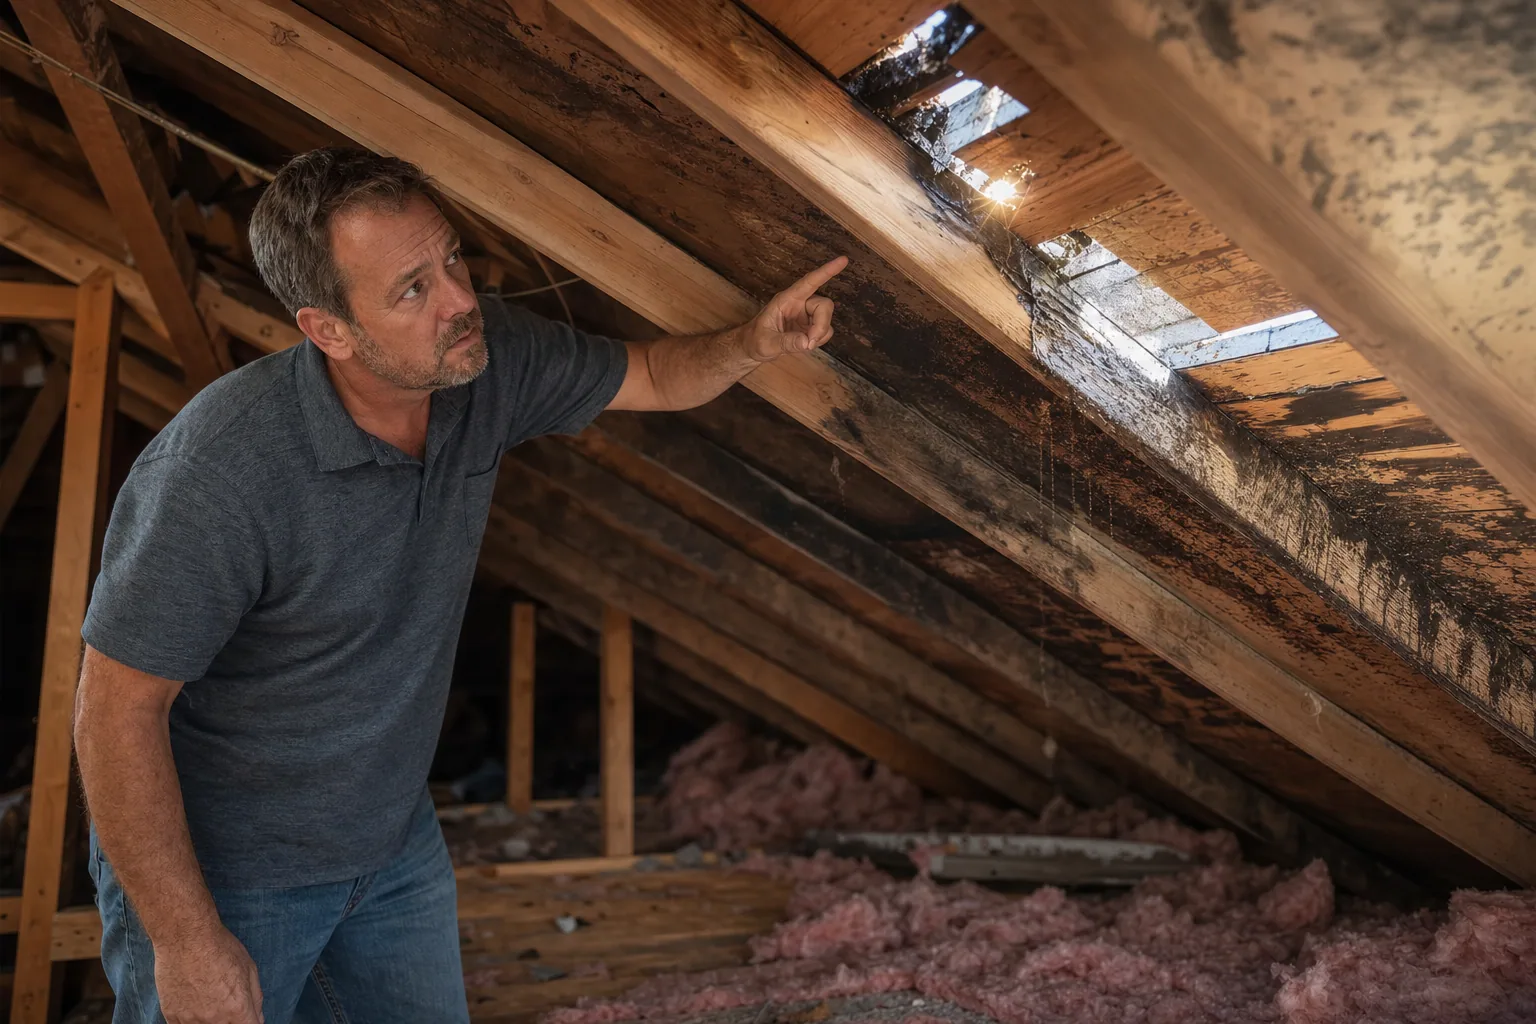
- The roof deck shows visible water damage or exposure
- Damage occurs after a documented storm event
Damage from age, poor installation, or lack of maintenance will not be covered. This is why detailed documentation from the moment you spot damage is critical.
Document Everything Right Away
Your insurance claim begins the moment you notice damage, not when you contact your insurer. Act quickly but safely.
- Take photos and videos from multiple angles while standing safely on the ground. Get wide shots showing the overall roof and close-ups of specific damage like missing shingles or lifted edges.
- Document the date and time you discovered the damage.
- Save weather reports from the day of the storm, including wind speed measurements if available.
- Keep receipts for any temporary repairs you make to prevent further water damage, such as tarping or patching. Most insurers will cover these temporary fixes.
- Do not attempt major repairs before your adjuster inspects the damage. Modifications can void your claim.
The stronger your documentation, the harder it is for an insurer to deny or undervalue your claim.
File Your Claim Promptly
Contact your insurance company as soon as possible after a windstorm. Most policies require notice within a specific timeframe, typically 30 to 60 days, though some states have different rules.
When you file:
- Have your policy number and coverage details ready
- Describe the storm and its impact clearly
- Provide the date damage occurred
- Mention any temporary repairs you have made
- Ask for the adjuster's contact information and expected timeline
Many insurers allow you to file claims online, by phone, or through their mobile app. Written documentation via email creates a useful record of when you filed and what you reported.
The Insurance Adjuster's Role
Once your claim is filed, an insurance adjuster will inspect your roof to assess the damage and estimate repair costs. This is a important step, and you have the right to be present during the inspection.
What the adjuster looks for:
- Signs of storm-related damage versus pre-existing or age-related wear
- The extent of damage across the roof
- Whether repairs can stop further damage or if replacement is necessary
- Current roof age and condition
- Compliance with policy terms and exclusions
Be present during the inspection. Point out all visible damage, including areas the adjuster might miss. If you have hired a roofing contractor like Trifecta Roofing and Restoration to assess the damage, consider having them present as well. A professional roofer can explain technical details and ensure nothing is overlooked.
When Your Adjuster's Estimate Seems Too Low
If the insurance company's estimate falls short of actual repair costs, you have options.
Many homeowners work with professional roofers who can provide a detailed estimate of repairs or replacement. Trifecta Roofing and Restoration can help you understand the true scope of damage and what repairs will cost. In some cases, insurers' initial estimates undervalue the work needed because adjusters are not always specialized in roofing.
If estimates don't align:
- Request a second opinion from your roofer
- Submit the roofer's detailed estimate to your insurer
- Ask your insurer to explain line items that differ from the roofer's quote
- Consider filing a request for reconsideration with new evidence
In Oklahoma, you may also have the right to hire an independent adjuster to dispute your insurer's assessment. This process, called an appraisal, involves both parties presenting estimates and working toward a fair settlement.
Working With Your Contractor Through Claims
Trifecta Roofing and Restoration works directly with insurance companies to simplify the claims process. This partnership makes a real difference for homeowners. Rather than navigating back and forth between your insurer and contractor, Trifecta communicates with your insurance adjuster, explains the damage, and advocates for proper coverage.
This approach has proven results. Homeowners working with experienced roofing contractors often see their insurance settlements increase significantly. One customer reported that with a few days of communication between Trifecta and their insurance company, their payout increased from 60% coverage to 95% coverage of the total repair cost.
Choosing a local contractor who understands how insurers evaluate roof damage and who has successfully worked through hundreds of claims puts you in a much stronger position.
What Happens After Approval
Once your claim is approved, you will receive a settlement check or a promise of payment. The exact process depends on your policy and the insurance company.
Some insurers issue one check for the full estimate. Others issue an initial payment and a second check once repairs are complete and verified. Many policies require you to get the work done within a certain timeframe, typically 6 months to 2 years.
Before you start repairs, confirm with your roofer what paperwork your insurer requires. Some want photographic proof of work completion. Others may send an adjuster to verify repairs before releasing final payment.
Protect Your Claim From the Start
The strongest insurance claims are built on clear documentation, prompt reporting, and professional guidance. Wind damage is common in Tulsa, and insurers expect to see well-documented claims.
If you are facing roof wind damage, take photos, file your claim, and reach out to a local roofing expert who knows how to work with insurance companies. Trifecta Roofing and Restoration understands the Tulsa area and the challenges homeowners face after storms. Contact us for a free inspection, and let us help you navigate your insurance claim with confidence. You can also read more about our roof repair and replacement work before you call.
Don't Let a Small Leak Turn Into a Total Roof Replacement
High winds and hail can leave hidden vulnerabilities in your roof that lead to costly interior water damage. Protect your home and your investment. Contact us today!
Frequently Asked Questions
How do I file a wind damage insurance claim?
Document the damage with photos and video from the ground before anyone touches the roof, note the date you found it, then contact your insurer with your policy number and the date of the storm. Make only temporary repairs such as tarping or patching, keep those receipts, and be present when the adjuster inspects the roof. Submitting a roofer's detailed estimate alongside your claim gives the adjuster a clear scope to work from.
What counts as wind damage on a roof?
Insurers typically recognize lifted, curled or missing shingles, bent or separated flashing, bent or detached gutters and downspouts, cracked or pulled-away fascia, and a roof deck showing water damage or exposure, all tied to a documented storm event. Damage from age, poor installation or lack of maintenance is not covered.
Can I make repairs before the adjuster comes out?
Make temporary repairs only, such as tarping or patching to stop further water damage, and keep the receipts. Most insurers will cover those temporary fixes. Do not attempt major repairs before the adjuster inspects, because modifications can void your claim.
What if the insurance estimate is lower than the repair cost?
Request a second opinion from your roofer, submit their detailed estimate to your insurer, and ask the insurer to explain line items that differ from the roofer's quote. You can also file a request for reconsideration with new evidence. In Oklahoma, you may have the right to hire an independent adjuster to dispute the assessment through a process called appraisal.