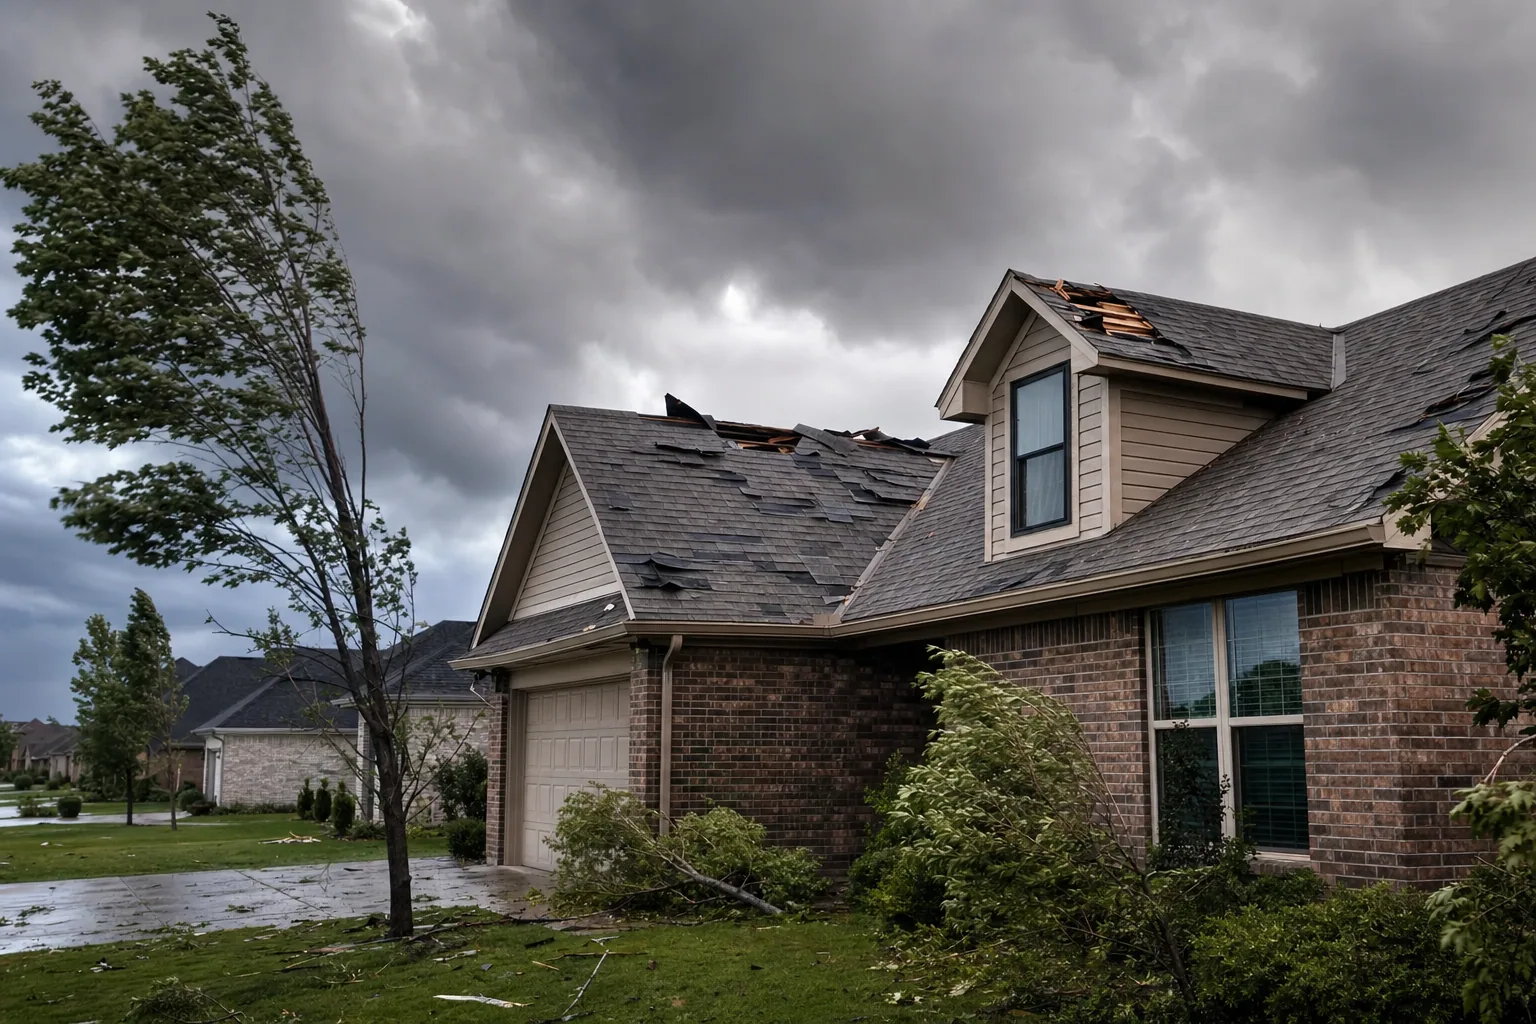
What Does Your Policy Actually Say About Wind Damage?
Most standard homeowners policies cover sudden wind damage to your roof, siding, gutters, and more. The questions that actually decide what you get paid are in the fine print: what your deductible is, what your policy excludes, and whether you carry a separate deductible for named storms.
This post is about coverage. If you already know you have damage and you're ready to start a claim, read our walkthrough of the process first: insurance claims for wind damage roofs.
Below, we go through what wind policies typically include, what they usually exclude, how wind and named storm deductibles work, and when it makes sense to get a second opinion on an adjuster's estimate. Trifecta Roofing and Restoration works with most insurance claims, so you're not left handling the paperwork and negotiations alone.
What Wind Damage Does Insurance Typically Cover
Homeowners insurance generally covers wind damage that occurs suddenly and unexpectedly. Common covered losses include:
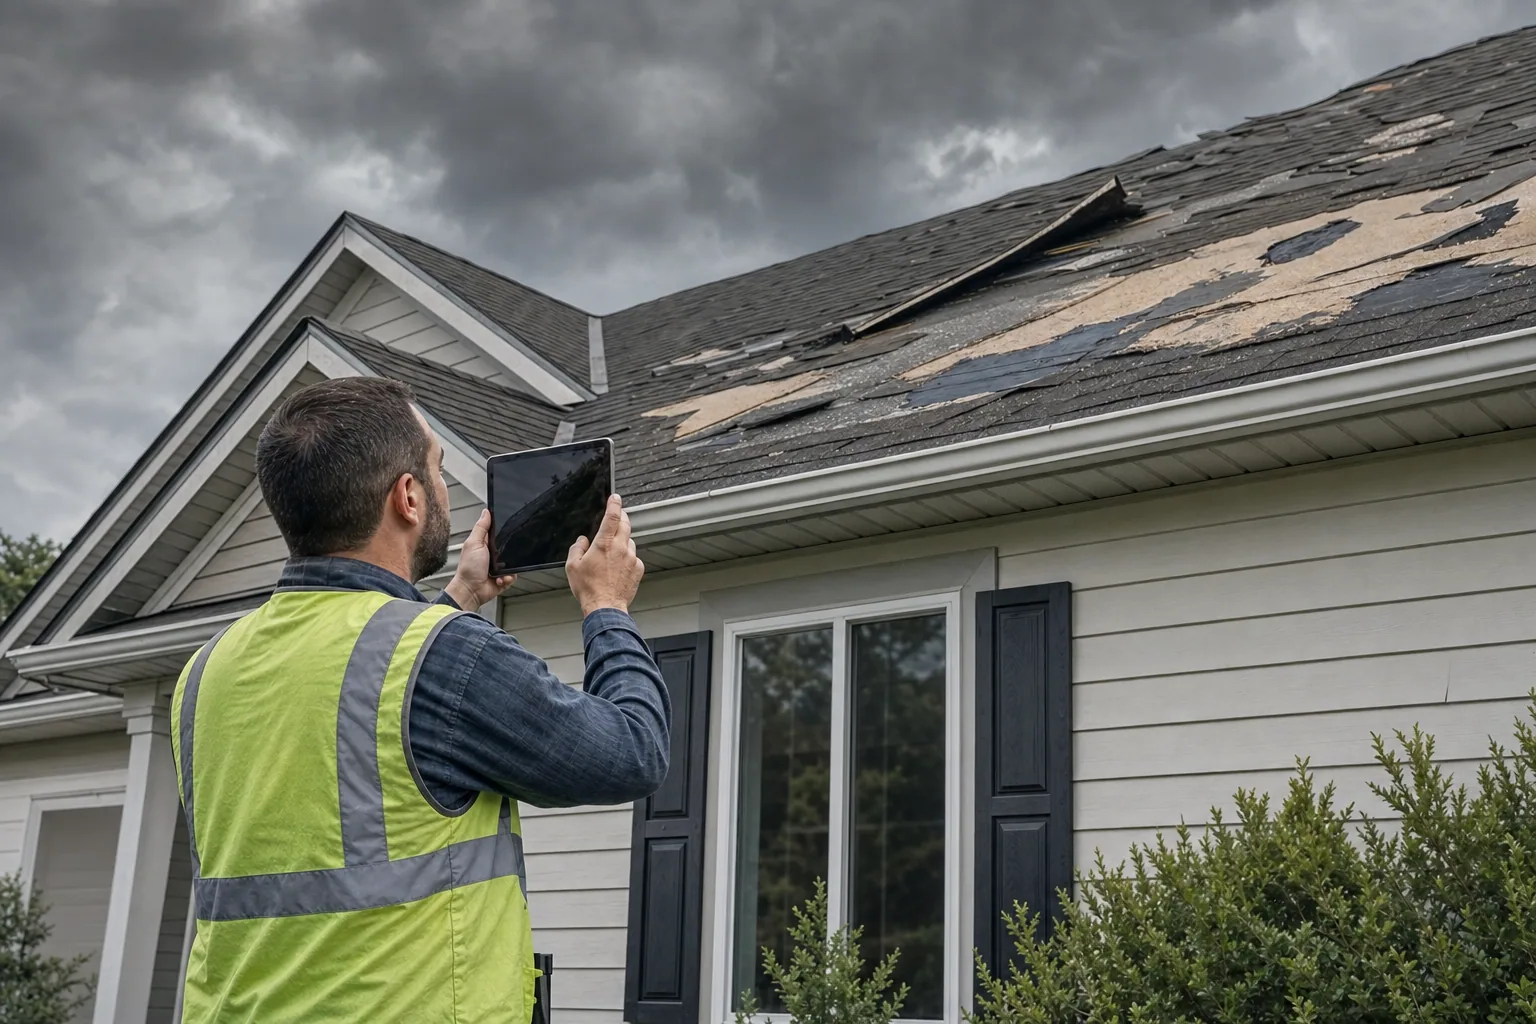
- Roof damage from high winds (missing or damaged shingles, lifted flashing, broken branches on the roof)
- Siding damage (torn vinyl, dented metal, cracks from flying debris)
- Gutter and downspout damage
- Broken windows and skylights from wind-driven impact
- Damage to fences, detached garages, and storage sheds
- Interior water damage resulting from wind-related breaches (like a hole in the roof)
The key word is "sudden." Insurance covers unexpected wind events like thunderstorms, tornadoes, and derechos. It does not cover gradual damage from years of exposure or negligence on your part.
Wind Damage Exclusions: What's Usually Not Covered
Not all wind-related damage qualifies for coverage. Common exclusions include:
- Damage from poor maintenance or pre-existing conditions (a weak roof that finally fails in normal wind)
- Wear and tear over time
- Damage from flooding (wind and rain together create a gray area; pure water intrusion may fall under flood insurance)
- Damage from hurricanes or named windstorms in high-risk areas (these require separate windstorm insurance)
- Damage to landscaping unless it falls on a structure covered by your policy
Some states and insurers also exclude damage caused by wind if the roof is over a certain age or shows signs of prior neglect. This is why maintaining your roof and documenting its condition can protect your claim.
Your Deductible Matters
Even when wind damage is covered, you'll pay a deductible before insurance kicks in. Standard homeowners deductibles range from $250 to $1,000, but in areas prone to wind and hail, insurers may impose a higher deductible specifically for wind damage, sometimes 2-5% of your home's insured value.
For example, if your home is insured for $300,000 and you have a 2% wind deductible, you'd owe $6,000 out of pocket before insurance covers the rest. This is something to review with your agent, especially if you live in Tulsa or surrounding areas where spring storms and hail are common.
Where Do I Find the Full Steps for Filing a Wind Claim?
Filing is its own subject, and we've written it up separately. The short version: you document the damage, report it to your insurer, get a damage assessment from a qualified contractor, and work with the adjuster through the inspection. For the full walkthrough, read insurance claims for wind damage roofs.
Trifecta Roofing and Restoration can provide a professional damage assessment and work directly with your insurance adjuster to ensure accurate estimates. Many homeowners are surprised to learn that a contractor's detailed inspection often increases the insurance payout significantly.
When to Get a Second Opinion
If your insurance adjuster's estimate seems low, you have the right to dispute it. This is where a local contractor like Trifecta becomes useful. We know Tulsa's building codes, material costs, and what storm damage actually looks like. If the adjuster misses damage or underestimates repair costs, a professional second opinion can lead to a higher payout.
One Trifecta customer reported that initial insurance coverage was quoted at only 60% of the repair cost. After working with our team and the insurance company, the final payout reached 95% of the job. That's the difference between a proper repair and a compromised fix.
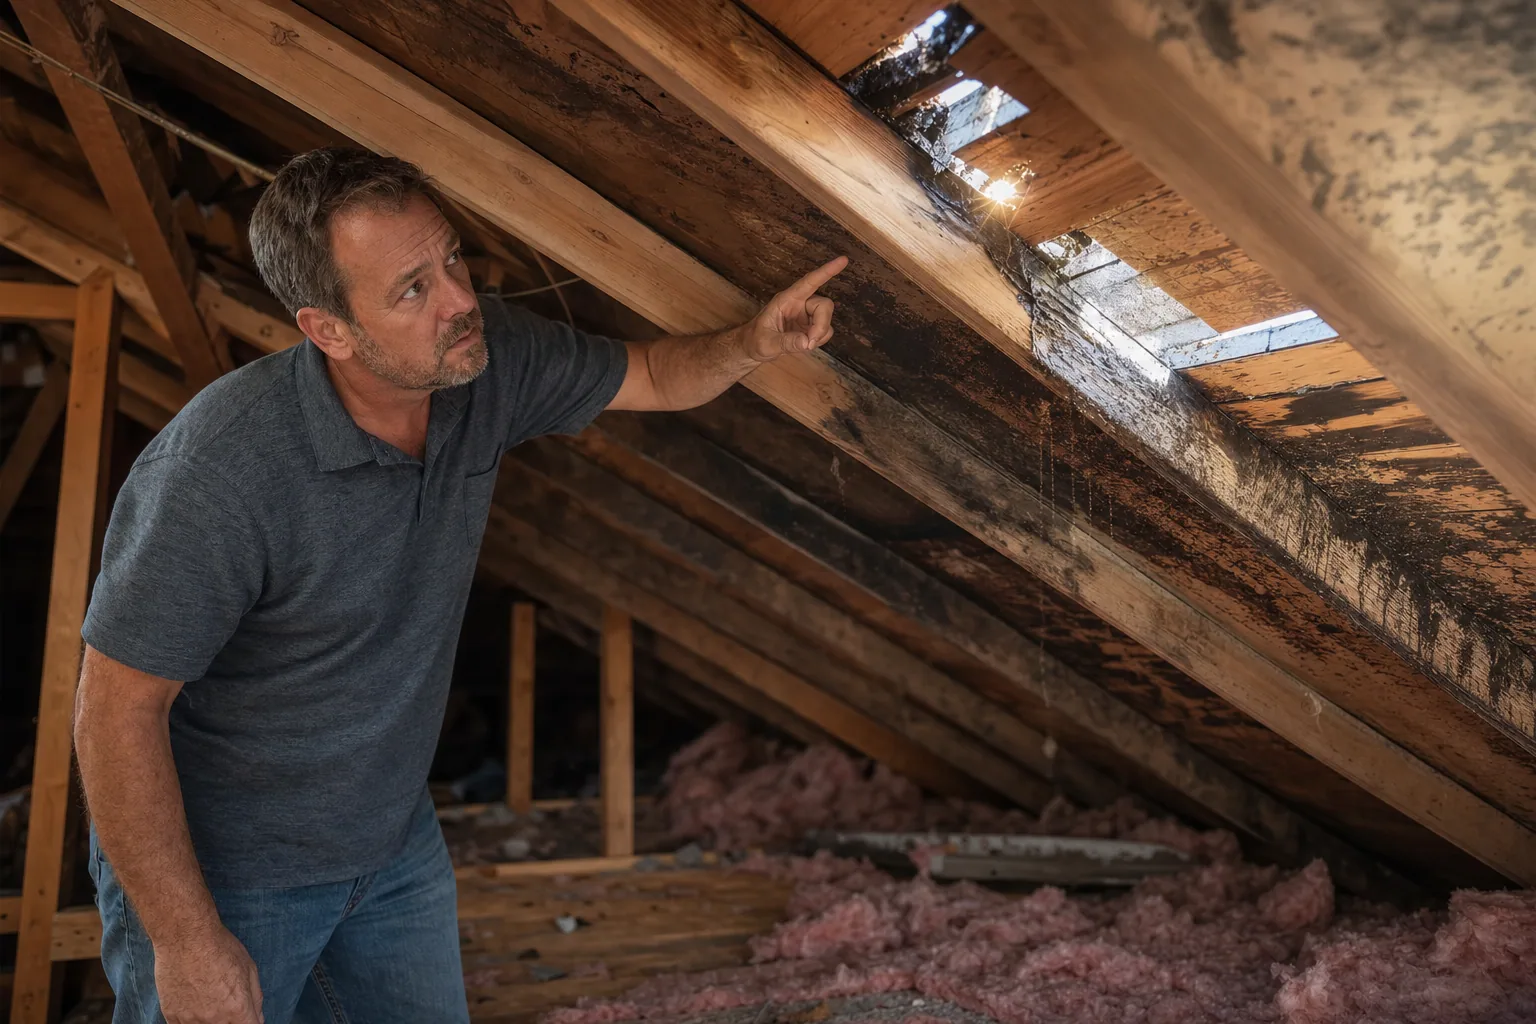
Don't Let a Small Leak Turn Into a Total Roof Replacement
High winds and hail can leave hidden vulnerabilities in your roof that lead to costly interior water damage. Protect your home and your investment. Contact us today!
Named Storm Deductibles and High-Risk Areas
If you live in a region prone to hurricanes or severe windstorms, your policy may include a named storm deductible that's separate and higher than your standard deductible. In Oklahoma, this is less common than in coastal states, but it's worth reviewing your policy.
Some insurers in wind-prone areas also offer "deductible buydown" options, where you pay a higher annual premium in exchange for a lower deductible when wind damage occurs. If you're in Tulsa County and storms are a regular concern, this might be worth discussing with your agent.
Protecting Your Home and Your Coverage
To maintain valid insurance coverage and minimize wind damage risk:
- Keep your roof inspected and maintained regularly
- Trim trees near your home to reduce debris impact
- Document your home's condition with photos and maintenance records
- Review your policy annually and understand your deductibles
- Consider impact-resistant roofing materials and wind-resistant upgrades
Trifecta Roofing and Restoration specializes in helping homeowners prevent water damage, improve energy efficiency, and restore properties after severe weather. Our storm repair services focus on preventing further damage, addressing safety concerns, and preserving your home's value, all while working directly with your insurance company.
The Bottom Line
Yes, homeowners insurance typically covers sudden wind damage to your roof, siding, and other home structures. But coverage depends on your specific policy, deductible, the cause of damage, and whether you've maintained your home properly. After a major weather event, contact your insurance company and a trusted local contractor promptly.
If you're dealing with wind damage in Tulsa or the surrounding areas, Trifecta Roofing and Restoration is here to help. We work with most insurance claims to simplify the process and reduce your stress. Contact us today for a free inspection and to discuss your repair options.